

Welcome to Original Jurisdiction, the latest legal publication by me, David Lat. You can learn more about Original Jurisdiction by reading its About page, and you can email me at davidlat@substack.com. This is a reader-supported publication; you can subscribe by clicking here.
Cryptocurrency is at a critical point in its evolution. The existential questions have been answered—crypto is here to stay—and now the main issues relate to how it will be regulated (and by whom). Last year, Congress passed the GENIUS Act, landmark legislation governing a particular category of crypto called stablecoins. And when it returns from its August recess, the Senate will consider the CLARITY Act, a comprehensive market-structure bill covering the entire digital-asset ecosystem.
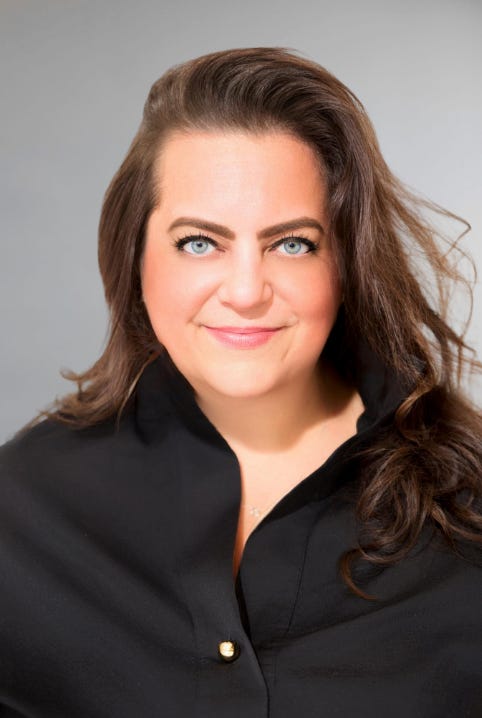
So Molly Abraham, who became the new general counsel of Coinbase last month, assumes her new role at an exciting time for her company—the nation’s largest cryptocurrency exchange—and for the crypto industry more generally. After reviewing her impressive legal career (and reminiscing about Wachtell Lipton), we covered the CLARITY Act, how Coinbase’s legal team is using AI in innovative ways, and how Molly believes the raging litigation over prediction markets will be resolved.
Thanks to Molly for joining me, and congratulations to her on becoming the GC of Coinbase.
Show notes:
Molly Abraham bio, Coinbase
Coinbase’s New GC Sees AI as Legal Department’s Biggest Opportunity and Risk, by Michael Gennaro for Law.com
Molly Abraham of Coinbase on Legal Leadership, Flying Cars, and The Art of Questioning Everything, by GC AI
Sponsored by:

NexFirm helps Biglaw attorneys become founding partners. To learn more about how NexFirm can help you launch your firm, call 212-292-1000 or email careerdevelopment@nexfirm.com.
Three quick notes about this transcript. First, it has been cleaned up from the audio in ways that don’t alter substance—e.g., by deleting verbal filler or adding a word here or there to clarify meaning. Second, my interviewee has not reviewed this transcript, and any transcription errors are mine. Third, because of length constraints, this newsletter may be truncated in email; to view the entire post, simply click on “view entire message” in your email app.
David Lat: Welcome to the Original Jurisdiction podcast. I’m your host, David Lat, author of a Substack newsletter about law and the legal profession also named Original Jurisdiction, which you can read and subscribe to at davidlat.substack.com. You’re listening to the 103rd episode of this podcast, recorded on Friday, August 14.
Thanks to this podcast’s sponsor, NexFirm. NexFirm helps small and midsize law firms offer Biglaw-caliber benefits at small-firm prices. To learn how NexFirm can improve your employee benefits program, call 212-292-1002 or email betterbenefits@nexfirm.com. Want to know who the guest will be for the next Original Jurisdiction podcast? Follow NexFirm on LinkedIn for a preview.
Last month, Molly Abraham became the new general counsel of Coinbase—the nation’s largest cryptocurrency exchange, as well as the first crypto company to join the Fortune 500 and the S&P 500. And she’s taking on this high-profile new job at an interesting and important time for the crypto industry. When the Senate returns from its August recess, it will consider the CLARITY Act, which would establish a comprehensive federal framework for regulating crypto markets.
In our podcast conversation, I asked Molly for her thoughts about the CLARITY Act, of course. But we also covered more foundational matters, for listeners who might not be that familiar with crypto—including what exactly crypto is, what some of its use cases are, and why Molly is bullish on its future.
We also talked about a number of other topics in the news—including AI, which Coinbase is using in innovative ways, and litigation over who can regulate prediction markets, an industry in which Coinbase is now a player. Without further ado, here’s my conversation with Molly Abraham.
Molly, thank you so much for joining me.
Molly Abraham: Thank you so much for having me, David. I’ve been looking forward to this all week.
DL: Tell us about your background and upbringing. Where did you grow up?
MA: I grew up in a little town called Edina in Minnesota. I’m a Midwesterner, born and raised.
DL: And did you have any lawyers in the family or any early exposure to law?
MA: I didn’t. My parents are not lawyers, I have no lawyers in the family, and my parents actually quite actively discouraged me from going to law school. But I was a policy debater in high school, so I got my real first exposure to legal issues in cases then and just totally fell in love.
DL: Why did your parents discourage you? You mentioned that you had no lawyers in the family, but you also said you didn’t have much exposure to the legal system. Did they have some kind of bad experience? Was it stereotypes about lawyers?
MA: It’s a great question; I might need to ask this at Thanksgiving. I think they just didn’t have that much exposure to it and didn’t know if this would be an area where I could reliably make a good living. And they had this thought that if I went into a more technical field like engineering, which is what they ultimately pushed for, that would better set me up for long-term independence and success. So for whatever reason, they had this mindset, and as a result, I am a chemical engineer practicing law.
DL: My parents actually encouraged me to go to law school, but I don’t know that they had a good understanding of what I did when I did practice law. Are your parents good with your current career?
MA: They find it super interesting. Every so often they’ll see Coinbase in the news. They’ll send me the article as though maybe I missed it, and I really enjoy that.
DL: You mentioned you are an engineer practicing law. After college, you actually did work in that field, correct?
MA: I sure did. I had done some internships at Procter & Gamble and then went to P&G full time as a product development engineer coming out of college. I worked for Pampers, their baby division, and had a great experience there.
DL: Excellent. And you always knew, I believe, that you wanted to go to law school during that whole time?
MA: I did. It was an interesting experience. I was living in Cincinnati. I didn’t know a soul. And so I would go to P&G during the day, and then I would quickly run over to the local Starbucks at night, where I would tutor students for the LSAT and work on my own applications, saving money for law school. And I always had my eye on law school.
DL: You went to the University of Chicago for law school. I have such huge respect for it as an institution. What did you think of your experience there?
MA: I really treasure my experience at UChicago. I actually married a classmate as well, so it has a special place in my heart for more than one reason. The law school community is such a special place. The intensity and rigor of thinking there is so unique. The principles-based reasoning that they instill from day one of that first class is really impactful.
Fun fact: every legal leader at Coinbase has been an alum of the University of Chicago Law School. We had Juan Suarez, Brian Brooks, and of course, most recently, Paul Grewal. I think there’s something about that rigor of thinking and that principles-based framework that meshes well with an industry like crypto.
DL: I definitely want to explore that; that’s an intriguing observation. But let’s finish up your career. Where did you go after Chicago Law?
MA: I joined Wachtell Lipton as an associate, a place I know we both hold near and dear to our hearts. When I interviewed at Wachtell, it was my second trip ever to New York City. It was before people were using iPhones, and I remember having to try to map out the directions of the firm; I still have the piece of paper, the map I printed out.
And when I left the building—really knowing almost nothing about corporate law, never having heard of a poison pill outside of a classroom—I thought, “I just have to work here.” The people, the intensity, and the intellect of everyone in that building—it’s just palpable. I’m so curious if you have a similar feeling or a recollection of it; it’s just such a special place.
DL: Yes, I totally agree about the intensity and the rigor. People would just get really into their work—you could argue maybe to a fault—and were just so enthusiastic about the issues they were grappling with. I suspect there are probably some commonalities between UChicago and Wachtell culturally.
MA: There are. And it’s funny because as you said that, I thought you were also going to say Coinbase, because it does feel so challenging and intellectual and rigorous here. The culture is very similar; it’s what’s made me love Coinbase the way I love Wachtell and UChicago. One of the unique culture points that folks may not know about the firm is this concept of attorney dinner. Do you remember doing that?
DL: Yes!
MA: Of course. And going to attorney dinner, you’d see the partners, because the partners were still there every night; they didn’t go home and leave the associates working the long hours by themselves. The partners at Wachtell are in it just as much as the associates. So everyone would take a break and go have dinner together and talk about the interesting legal issues they were working on. And there was just this intellectual curiosity and love of the game that everyone there has that is just so unlike anywhere else.
DL: I totally agree, and I do have those memories. The attorney dining room has been relocated from where it was in my time, but I remember the tax people would sometimes have their code books at the dinner table. It was a very… “intense” is definitely the right word. You spent quite a bit of time at Wachtell, right?
MA: I did—almost seven years. I got to work on some really interesting cases. I was a litigator while I was there, even though I left my litigation days behind a while ago, and I got to work on some really interesting cases—including seeing a jury trial all the way through to a verdict, which is not typical for many associates and was just a ton of fun.
DL: Where did you go after Wachtell?
MA: So we had made a move out to the West Coast. My husband—whom I met in law school, he’s a J.D./M.B.A. from Chicago—got a great job on the West Coast. We had had our first son. And so out to California we came, and I joined a company called Kitty Hawk, which made flying cars. It’s a company co-founded by Google X founders, including Sebastian Thrun, who is the CEO and was originally responsible for the self-driving car project at Google. So we took it to the skies. It was an absolute blast.
DL: You got an in-house job after working at a law firm. During my brief stint in recruiting, I quickly learned that in-house jobs were what everyone at a firm was aspiring to—the golden ticket, the Valhalla, or whatever you want to call it. How did you land that job?
MA: Honestly, it was a lot of conversations, but I’m going to share a career tip for folks in this moment. We moved out to the West Coast. I actually left the firm without having gotten a new job—you’ll be shocked to know it’s not actually possible to bill 3,000 hours a year and search for a job on a different coast. So I went ahead and said, “Leap of faith—I know I’ll find something great.”
So we moved to the West Coast, and I just started meeting people. And I think so often people approach networking as, “Oh, well, keep me in mind if you ever hear about something interesting.” I took a different approach, which I recommend to anyone looking for an in-house job.
To every meeting, I brought an 8.5 by 11 piece of paper, and I divided it into company stages—early-stage startups; pre-IPO, late-stage companies; and public companies—and then a couple of different areas of tech that I was interested in. And I basically used this chart, and I wrote down company names. And I would say to someone, “These are the companies I’m thinking about that could be interesting, in terms of what I want to explore. What company is missing from this list?” Everyone has ideas, and when they see a chart, their inclination is to help fill it in. And then I would say, “Is there anyone from one of these companies you can introduce me to?” And it turns out nobody wants to say, “No, in fact, I’m completely unconnected. I have no introductions for you.” And so every one of those meetings would turn into at least two introductions. My parlor trick is I would say, “Would it be helpful if we just shot those emails off right now? I have a draft that you could send about me.” And from each of those meetings, it was super helpful.
I got more intros, and it was a second- or third-order intro where I spoke with someone from Kitty Hawk and then ultimately was introduced to the company. And when I walked in and met with the team, I had that same feeling when I walked into Wachtell, and ultimately later when I walked virtually into Coinbase, which was, “These are people I want to spend every day with.”
DL: And what was your role at Kitty Hawk?
MA: So I joined as their second lawyer, and within about a year I became the general counsel. I was there for about four years. My legal team was tiny, but mighty. We were just about five folks total. Although I also, slowly over time, was placed into the “this woman can get s**t done” category—excuse my French. And so I also took on finance and HR and basically all of operations.
Ultimately, it was an incredibly important experience career-wise for me, for two reasons. One, it really taught me that I love to lead large teams and that being a subject-matter expert is not the end-all be-all. I don’t have a finance background, but I was effective at leading the finance function because I knew what mattered to our founders and the rest of the exec team, so I could help the finance team figure out how to translate the way that mattered. So that really led me to loving to lead large teams. And then the other thing that I did there was I truly became a deal lawyer instead of a litigator. I led our company through a significant M&A transaction with Boeing where we created a joint venture that ultimately Boeing wholly acquired years later, and just this week Archer acquired. So I had the opportunity to approach deals having been a litigator, understanding all of the ways deals can go wrong, which I think has also really shaped me as a deal lawyer.
DL: Interesting because, again, a lot of people who do get in-house opportunities come from more of a transactional background. So it’s interesting, what you were saying about how that litigation background helped you. So where did you go after Kitty Hawk?
MA: After Kitty Hawk, I joined Coinbase. Let me offer one more unsolicited career tip, which explains how I originally chose Coinbase. It’s very easy to think about, “What do I want for my career two years from now, or one year from now?” But I think the right arc to think about is actually the five- to eight-year mark. So when I was leaving Kitty Hawk, I knew that what I really wanted to do was to ultimately be the GC of a public company, whether it was to take a company public or to become the GC of a public company. And in talking to recruiters, I learned that a really key part of a late-stage private company wanting to hire a GC is public-company experience. So I approached my search at that time as, “I need to find a place that’s a great fit for me”—which is number one, for me, always about the people—“but I’m also building towards a longer career arc.” And it might mean that this particular path or role is not exactly the next sequential step on that ladder and maybe a bit more sideways, but it’s all part of collecting these pieces to give me the experience for what I ultimately want to do.
So when I joined, I interviewed with a number of super-late-stage or late-stage private or early-stage public companies, and Coinbase was getting ready to but had not yet gone public. And when I interviewed with my then-manager at the time, they were doing tons of hiring, and I said, “What kind of roles do you have?”—I was not interviewing for a specific role—and she said, “Our commercial team is most in need of support.” And pure commercial deals were not my bread and butter, but she said, “This is the area that most needs to scale,” and scaling is my bread and butter. So I said, “Sign me up. Sounds great. It may not be the exact role I would have designed for myself or chosen, but the company was right and the people were right.” So I tried to maintain some flexibility in how I thought about the role itself.
DL: That’s such an important career point, because a lot of times people think, “Oh, I just need the perfect thing.” But sometimes you can sort of, I don’t know—I’m not a sailing person, but people say it’s like navigating a sailboat: You tack this way and tack that way, and you’re not necessarily always going directly to the point you want to get to. So I understand what you’re saying.
MA: My other favorite analogy is it’s like looking for an apartment in New York (so maybe this is speaking our language, David). You can’t have the perfect location, the perfect unit, and a great price; you’re going to compromise on one of the three. And I tell folks who are interviewing for various roles this all the time, which is it’s not going to be the perfect company, the perfect role, and the perfect comp; you’re going to compromise on something. So just figure out what’s most important to you. What’s most important to me is finding people that I want to be in the trenches with every day. I’m an intense workaholic; I want to be with people who are that excited as well. And that’s been consistent across the companies I’ve joined.
DL: When you joined Coinbase, what experience did you have with crypto? What was your knowledge or familiarity level with crypto?
MA: It was zero. I signed up for my Coinbase account during the interview process. I had been reading about the company; I heard great things. I bought the book Crypto for Dummies; it’s still sitting on my desk as a memento. I’ve never opened it because I learned so much on the job immediately. And the thing that I’d always coach my team on is you have to use the products to be able to understand the legal issues related to them. So I just started really using the products, any trader or salesperson who was willing to get on the phone with me and walk me through their favorite product or how it worked, and I really used that as my basis. I felt that the company was doing interesting things; I felt it was mission-aligned. So the love of crypto came second to me, after attraction to the team, the people—and to be honest, just Paul’s amazing reputation as a legal leader, as a judge in the legal community, that was a really big draw for me more than crypto. But the crypto has definitely kept me here; I love it a lot.
DL: Let’s explore that. I’m often surprised by how many people either don’t know that much about crypto or just don’t have much familiarity with it. If you were at Thanksgiving with your relatives—non-lawyer, non-finance, non-tech relatives—what is crypto? Give us your sort of elevator explanation for it. And how is it useful? Because another thing you’ll hear about crypto for people who are not that familiar with it is, “Oh, isn’t it just used by criminals for illicit purposes?” So what is crypto?
MA: Crypto is digital money. It’s part of an open financial system for the internet. One way to think about it is just like the web gave everybody equal access to information and really democratized information access, crypto gives everyone equal access to money. You could have direct ownership of your assets. You don’t have to have a middleman. You can transfer value more easily and without permission.
And maybe to make it a little more real, let me talk about a couple of baby use cases or how I use crypto, if you will. I buy Bitcoin; I’m buying the dip right now. It’s a great time to buy. And I also use it for payments. If we’re throwing a baby shower for someone at work, we all just transfer money to someone’s wallet, instead of Venmo. It’s instantaneous, it’s cheap, it’s fast. We have our own layer-two blockchain that we’re able to have these sub-second transactions on.
Another area that I’m particularly passionate about are stablecoins. Stablecoins are cryptocurrency that are literally stable. They’re pegged—for example, USDC is pegged to the U.S. dollar, and so it’s always worth a dollar. It’s a really easy way to transact without necessarily investing, for example, in Bitcoin, which changes in value. And so we saw the GENIUS Act passed last summer, it was “Stablecoin Summer,” and I think it’s only going to continue to increase. I think it’s going to really replace a lot of financial rails. If you think back to TradFi concepts, if you’ve heard of “T+3” or “T+2,” when people use those phrases, they are referring to how long it takes to settle money—for example, the idea that a wire takes two days. Crypto changes all of that. It makes it instantaneous, and it’s way more accessible.
DL: You mentioned Venmo. I think traditional finance institutions have tried to make their payments go through more quickly too. You have Venmo and Zelle and Quickpay and what have you. So what is different or better about crypto versus, I guess—did you call it TradFi? Is that traditional finance?
MA: Traditional finance—I’m so used to that phrase at this point. But yes, with crypto, it’s sub-cent, sub-second transactions. So it’s cheaper, it’s faster, and it doesn’t require a middleman. You and I could send crypto back and forth to one another, and it could be USDC. It could be stablecoins, stable value. I could pay you for a contribution to a baby gift, and it’s going directly to you. It’s not getting routed through multiple different parties, which in and of itself can introduce different risks. So I find it to be really powerful. I think stablecoins were a huge initial use case, and it’s also a great way for people to get started if you’re not as interested in trading in assets that change in value.
DL: If you’re the managing partner of a boutique or midsize law firm, attracting and retaining great people is your most important responsibility. Competing with Biglaw for talent is difficult when your benefits don’t measure up. NexFirm helps you offer Biglaw-caliber benefits at a price built for smaller firms. To learn more, call 212-292-1002 or email betterbenefits@nexfirm.com.
So you mentioned buying the dip, and what you’re referring to is that right now the crypto market is in the doldrums. The total cryptocurrency market cap is estimated at around $2.1 or $2.3 trillion. At one point, it was as high as $4.3 trillion. So with the caveat that nothing on this podcast is investment advice, and nothing is legal advice, it sounds like you are long-term bullish on crypto?
MA: Oh, I’m super bullish. It’s interesting. There’s actually a really cool chart—I’ll have to find it and send it to you—where basically the ups and downs of crypto over time are on this graph. And it’s not like a sine curve—I’m sorry to totally “enginerd” out on you—where it’s just up and down and up and down in a steady state. Yes, there are ups and downs—I think that the crypto market can feel more volatile at times, or it feels like it has these deep peaks and valleys—but these peaks and valleys are all on an upward slope. So I think that the long-term future of this market is super strong. I’m super bullish on it. I think that the passage of legislation like the GENIUS Act and the forthcoming (hopefully) passage of legislation like the CLARITY Act is only going to continue to increase adoption and make this something that’s increasingly accessible to a wider swath of consumers.
DL: Full disclosure to my listeners: I share your optimism. Every month, I put a small amount into crypto—I have the Coinbase app—again, a very small amount, but I do it every month.
So you alluded to regulation. You talked about the GENIUS Act, which was passed last year, which regulates stablecoins. And then right now the Senate is in recess, but when they return, they might vote on the CLARITY Act, which you mentioned just now. And if passed, that would be the second major piece of legislation in two years, after last year’s GENIUS Act. So can you explain, in a nutshell, what is the CLARITY Act, and what would it do? And does Coinbase have a position on it?
MA: Coinbase is super supportive of the CLARITY Act. We have long been advocating for clear rules for this industry. Just to take us back a step, at one point, Coinbase advocated and sought for the SEC to do rulemaking—and first it was silence. We ultimately took them to court to at least get them to answer the question, “Will you do this?” And after they lost in the Third Circuit, eventually they effectively said no. They sued Coinbase and other exchanges instead—and ultimately withdrew those cases with prejudice. It has been a wild ride in that sense. So I think it’s important context because there was this era of regulation by enforcement. And so part of what CLARITY helps do is set the stage going forward. Yes, we have ended the era of regulation by enforcement, but it’s important to show, on a go-forward basis, that there is a clear set of rules for this industry.
And so CLARITY does that. It’s one of the most important and strongest bipartisan bills the crypto industry has ever seen. It has the backing of a really interesting variety of players that have all come together, whether it’s law enforcement groups, the White House, you name it. And very recently, a lot of progress has been made to resolve a variety of open issues. And now it will be up for a vote—I think it’s September 15th, don’t quote me on that, but I think that’s what the Senate said as their timing when they return from recess. What’s important about CLARITY is it will help bring uniform U.S. rules and oversight under a number of different agencies. And so it just really sets predictable and clear standards going forward, which is what Coinbase has always advocated for.
DL: Does it identify a primary regulator for the crypto industry? Because as you mentioned, the SEC was very active in this space, and then it suffered a number of setbacks, and some people have also advocated for the CFTC to be a big regulator. Does the CLARITY Act clarify who has jurisdiction over crypto?
MA: So the answer is a little bit of both. It does address, on a topic by topic basis, who the right regulator is. The CFTC has a very significant role regulating crypto spot markets, and the SEC will also have an important role as it relates to the potential for crypto securities. And so the good news is we have a hundred years of experience in this country navigating between different types of asset classes, and crypto is not just one thing. I think that the power of tokenization or digitizing different types of asset classes is that it cuts across asset classes. For example, you could have tokenized securities. We just launched them out of Abu Dhabi this week, to be able to have tokenized equities—so you can have a tokenized version of NVIDIA, for example—but there’s also a variety of spot and derivative products. And so there’s a huge range, and I think that there are federal regulators who are ready to step up to the plate and provide clarity for this whole industry.
DL: Let’s turn to your new role. You very recently became the GC of Coinbase, and you mentioned earlier that your goal was to become the GC of a public company, so congratulations. What would you identify as some of your priorities in your first year?
MA: One of the really exciting parts about taking the GC role at this time in Coinbase’s history is that Paul Grewal, my beloved former CLO here, really paved the path to get us out of this period of regulation by enforcement. He won the SEC battle. He was able to help shape how far we’ve come on legislation. And so now I have this amazing greenfield in which to seek all of these opportunities for the company. And so while sign me up for litigation as it comes—my Wachtell days will stand me in good stead—the thing that really makes me most excited about this next phase for the legal team is what product opportunities we can unlock.
So that’s things like coming up with the way that we were able to do tokenized equities out of Abu Dhabi to be able to give a full set of shareholder rights in a tokenized form. Super interesting securities laws issues, and it’ll be more of things like that where we’re able to do innovative products to really delight our customers and find new ways to use crypto. The reason I love this field is because it’s so new, just like flying cars. There’s no perfect set of existing laws for it. So you’re always operating a little bit in the interpretation zone and it makes it really, really interesting and really hard, which I love.
DL: On the flip side of opportunity, there is of course danger or threat. What are the things that keep you up at night in your GC role?
MA: The number one thing keeping me up at night—and I hope it’s the same thing keeping everyone else up at night—is AI. Honestly, every so often I will be driving down the road and I’ll say to myself, “Why am I so stressed right now?” And it really will be because I think we’re wanting to adopt AI faster. I think that some of the work that we’re doing to adopt AI at Coinbase is probably on the cutting edge of what I’ve talked to any other legal team about, and I still feel like it’s too slow. I wish I had all the time in the world just to focus on the technology—and it’s hard to do that on top of leading the legal team and dealing with whatever crisis comes my way. Part of the way I’m going to try to solve that is I’m in the process of hiring a full-time engineer for the team, to be a forward-deployed engineer who will help us really set up this framework. But even though we’re going so fast, it does not feel fast enough.
DL: So it seems like your anxiety is not taking full advantage of AI, as opposed to “it’s going to bring about the downfall of human civilization” or “the robots are going to take our jobs” or something like that.
MA: Spot on. I think it’s amazing. I’m definitely in the camp that AI is not about replacing existing jobs; it’s about replacing routine tasks, and it’s going to create more economic activity. It’s going to make every company more successful, as opposed to making every company as successful as they currently are with less resources. This is about more economic activity and more productive teams and doing more strategic work, as opposed to anything else.
DL: I do, I think, partake somewhat of your optimism. I hope we’re right. Let me ask you this then. You talked about how you believe your in-house legal team at Coinbase is really at the forefront in some ways of integrating AI into your work. Can you give me some examples or some use cases or some things you’re doing with AI at Coinbase that might be new or different or that maybe a couple of years ago you never would’ve thought possible?
MA: Absolutely. I’ll share two examples. One is that we’ve come up with agents that literally are replacing entire tasks or a whole scope of work of a human. For example, we have a very, very active investment portfolio. It’s the type of thing where we get hundreds of emails a day. It then requires doing a variety of legal documentation related to all of these inbound documents. At this point, we used to have multiple people triaging this every single day, in a very manual way. Now it’s all just a single agent. And now those folks are able to do other, harder, more interesting work. And so we have a number of agents—I will tell you my biggest issue right now is figuring out a naming convention for them, so I’ll take any and all great ideas—but these are agents that we have active in our Slack. We interact with them, we ask questions, we give feedback, it’s a super powerful tool, and it’s really freed people up to do more exciting work and more interesting work. So that’s one.
And then the other I’ll share is that I considered writing to be my superpower as a lawyer. I think that I’m able to write in a way that can translate complex legal concepts to an executive, non-legal audience. I think I can do it with brevity: “If I had had more time, I would’ve written you a shorter letter.” And the thing that I said was, “AI could never write like me.” It turns out it can, and I’ve created an agent to do all of my drafting and editing at this point. By feeding it a ton of instructions and some of my best precedents and writing samples, as part of an iterative process, now the first draft of just about any document I do is AI-based. And my team uses it, because I used to edit other people’s work quite a bit before, for example, it would go to an exec audience; I would say, “Okay, here, I’ll take my red pen to it.” Now they put their drafts through the agent, and I have no comments. So it’s freed me up in a really significant way to do other things and to take on this big challenge as GC.
DL: You must have trained it very well, because a lot of people complain about AI writing; they say it sounds stilted or all sounds the same. But you have probably created some kind of “Molly Writing Agent.”
MA: That’s exactly what it’s called, it’s the Molly Writing Agent, and it’s very specific to my writing style. I will say the one downside is I’ve been an em dash user my whole life and it’s one of the tells of AI, but it’s also a Molly tell. And so I will not give up the em dashes just for the sake of not having it look like AI.
DL: I agree with you. I actually also love the em dash; it’s a very versatile and useful piece of punctuation. But let me ask you this burning question, which I’m actually going to post on LinkedIn: Do you put spaces before and after the em dash, or no?
MA: Absolutely not! Do you?
DL: I don’t currently, but I write this column for Bloomberg Law, and they have changed their house style to do that, and now I’m wondering whether I should do that on Original Jurisdiction.
MA: Absolutely not. I’m deeply opposed. I feel more strongly about this than any topic we’ve discussed today.
DL: So let me ask you this. You are clearly using AI for a ton of stuff at Coinbase. Has it changed your approach to hiring outside counsel?
MA: The outside counsel piece is interesting and challenging because outside counsel is struggling with how they cabin data. I think they have a data governance challenge that they are very much working through, because as they want to use AI and train AI, they have a lot of ethical obligations to not use your data in particular ways. I’ve had some really interesting conversations with different firm chairs about how they’re approaching the data-governance issues. As you and I both know, law firms don’t always run exactly like a business. And so the idea that all of a sudden they have to become incredibly technologically savvy is hard. We do have expectations of outside counsel in terms of their AI practices, both in terms of protecting our data and the fact that we want them to use it for certain types of tasks. It’s part of our firm billing guidelines at this point.
But I would say the most radical change I have seen vis-à-vis AI and outside counsel is just a change in where we’re using OC. We used to ask outside counsel to do a first-pass legal memo on a new and challenging new product—for example, when that implicated some particular area of law. Today, we would no longer ever ask them for a first draft; we know that we’re more attuned to the various AI tools and the ability to create a first draft. Now what we’re asking them for is to review our own AI-drafted memo. And so I think it’s going to have to change how law firms bill. I don’t think they’ve yet figured this out, and it’s still the case that I think a great partner in any given law firm is able to give such strategic advice, based on having seen such a volume of different types of situations, that would be very, very hard to replace. But in terms of some of the associate-level or more rote drafting work, at this point, my expectation for my team is that they do it themselves—and if they need an outside-counsel check on something bespoke, that’s fine.
DL: Do you expect your overall outside counsel spend to decrease, or are you just going to get more work for the same amount of money?
MA: I expect it to go down. I’m paying for this engineer just out of savings from first-half-of-the-year outside counsel fees, to be totally honest, because we have already changed how we’ve approached things, and it’s been enough to be able to fund bringing on this full-time engineer and maybe more.
DL: Interesting. So I don’t know—maybe some of my law firm listeners will be a little concerned. You mentioned the issue of data governance. Does your standard engagement letter, retention letter, what have you, have a provision about that? Or if you are using a law firm’s form, do you have a particular requirement as to how your data is treated?
MA: We do. And it’s not just for law firms; it’s also for any of our vendors. And I think that both as a note to your law firm listeners and to all of your GCs and in-house legal listeners, one of the most important things that every in-house lawyer needs to do is make sure that you are protecting your company’s data. Reddit had some really interesting lawsuits along these lines.
And even for us, one of the first things I did when AI started to become more common a couple of years ago was have our commercial team do a scour of all of our agreements, in terms of the ability to use our data to train other people’s models, because either I don’t want that happening without my consent or you can pay me for it. And that’s really important.
There was a company, I want to say about 18 months ago, that tried to just send an email notice to all of its clients that it was going to be using thousands of companies’ data to train its model and that this was going to be an exciting new product, and the backlash was immediate. And so I think that it’s really important that any GC is viewing AI through a couple of different lenses. One is a protector of your company’s data. One is an enabler of your company, because there are so many legal issues that come up as companies try to use more and more AI tools, so you want to be able to enable that quickly. It’s using it to scale your legal function. And then it’s being an individual super user. I’ve talked to a lot of GCs who have said, “My team is using it. I haven’t really figured out my personal use case though yet.” My super-user era came later than my general excitement about AI, and it wasn’t until I was using it in my daily work that I fully appreciated that power was going to bring.
DL: On the one hand, I can understand your being concerned about your Coinbase client data being used by a law firm to train AI tools, but I have wondered: do we have some kind of “pay it forward” duty as users of AI? We all understand that the AI is only as good as the stuff it’s trained on. To what extent do we have a responsibility to help make the AI better? Because if everybody says, “Oh, you can’t train on my stuff,” are they going to have anything to train on?
MA: Well, I feel like you’re going to the heart of the open-source question. These companies are not largely making their models open source. That needs to be led at the LLM level; my use of particular data is downstream of that.
But right now, if I were to let folks train on data, whether it’s my personal data or it’s company data, to what end? To make their model better, so they can go charge a different company for it? And this is where I do think the open-source question matters. I’m not 100% up to speed on the latest in that debate, but it’s a fascinating one. And it’s going to be really important because this is going to be one of the biggest technological innovations of our time, and how people are able to partake in it is a really critical question.
DL: With the rise of AI, have you changed your billing arrangements with law firms? You mentioned that it has affected your billing guidelines or your protocols, but I guess what I’m asking is, are you using the billable hour less, or not really?
MA: We have largely moved away from the billable hour as a company. We really do seek to do alternative fee arrangements, and that is increasingly a demand of law firms—to really think thoughtfully about outcome-based and other types of fee arrangements. And I would say that’s pretty independent of AI. We have a tremendous legal ops leader who’s been really at the cutting edge of all of this. To the extent that the law firms have been able to hold onto the billable hour for this long, I think the day may have come. I think it may be over.
DL: So let me ask you just a very open-ended or general question. How well do you think outside law firms are using AI? I don’t know what you’d say if you were to give them a letter grade. Or what are some cool things you’ve seen them do? Or things that they should be doing with AI that they’re not?
MA: Honestly, I don’t think they get a very good grade right now. I truly think they’re still trying to sort out how best to use it. And I think that firms are trying to use it enough to show recency and relevance, but I don’t think they’ve figured it out yet. I really don’t. It’s really going to distinguish the firms that become successful businesses from those that don’t.
We’re in really, really early innings, though—the warm-up stage of the game when it comes to law firms and AI, to be honest. And look, part of it is demanded by their clients. There are certain clients out there who won’t allow a firm to use AI. We’re seeing this with the law schools, right? No one’s really sure of the right thing to do; everyone’s experimenting a little bit. Some law schools are banning the use of AI; others aren’t taking a stand yet. I like what UChicago is doing: They effectively are saying, “We want you to embrace it in certain settings, and in others, we want you just to come to the room with your mind and nothing else.” And so I don’t think the law firms have figured it out. I don’t think the law schools have figured it out. Those who can be thought leaders in this space will be well-equipped for success.
DL: That’s totally right. And there has been research showing that in-house legal departments are actually ahead of law firms in AI adoption. So there you go.
MA: That tracks.
DL: So one thing that we’ve been hearing about a lot is the rise of prediction markets, like Kalshi or Polymarket, where people can essentially, I guess you could say, “bet”—I put that in quotes—on the outcomes of real-world events. And I believe Coinbase has announced something in this space?
MA: Yes. So we have a prediction-markets feature; we have it live in the app. Check it out in your app after this call, David. It’s a really interesting way to engage in event contracts. And litigation over prediction markets is quite intense. I think there are lawsuits in over 25 states. And part of the reason for this is for many years, various states have regulated this space or adjacent spaces, if you will. And with the advent of prediction markets, prediction markets are swaps under the Commodity Exchange Act, and so there’s a single federal regulator for swaps, and that is the CFTC. And so this issue has really come to a head with the growing success of companies like Kalshi and Polymarket’s U.S. version of their product and a number of other companies, Coinbase and many more, have also integrated this into our apps.
I swear, six months from now, we’re probably going to have part two of this conversation because this is going to the Supreme Court, David. We have a circuit split developing. The Third Circuit decided in favor of the prediction markets that, yes, there is exclusive federal jurisdiction. It’s the only appellate court to rule so far. But cases in the Fourth, the Ninth, and the Sixth Circuits have all been argued, not decided. So this is brewing for a really interesting case when it comes to whether the CFTC does have exclusive jurisdiction. We think they do. The CFTC chair has been very clear about their jurisdiction here and has stepped in. The clear answer is one federal regulator, but we’ll see a lot more lawsuits before we’re able to ultimately resolve that question.
DL: Again, I’m not an expert in this issue, but my gut is it does seem like these event contracts, which involve people and issues from across the country or the world, do seem ripe for one regulator, as opposed to 50 different regulators—that just seems kind of like a nightmare. But as you were saying, the litigation is crazy. It’s even hard to keep track of: “Okay, this state sued the federal government and the federal government sued them back, and the state is prosecuting Kalshi, and Kalshi wants a declaratory judgment against the state.” It’s very confusing.
MA: It’s complicated. I probably get at least one update per day on a development in one of these prediction-market cases. But one thing that is really refreshing, and that helps a lot, is when this litigation started, the CFTC had not yet shared its explicit view. The CEA is quite clear that the CFTC is the exclusive regulator for this space, but the CFTC had not yet spoken up. And they have since, and they have taken a really active role in this litigation. I think they’re actively litigating in maybe eight or nine of the states to protect their exclusive jurisdiction and the integrity of these markets nationwide. The result you would have otherwise, as you mentioned, would be messy. It would be chaotic. It would mean that if as you go from one state to the next, you would have to close positions. It’s not what’s best for consumers. It’s not what the CEA calls for. And so I’m hopeful that this gets resolved sooner than later, but it is a fascinating area to watch.
DL: Is there any talk of federal legislation, or do you think the resolution is going to come from the Supreme Court? Or how is this issue, at least in the near term, going to be resolved?
MA: I think it will be resolved by the courts. The CEA is already pretty clear that swaps are exclusively regulated by the federal government and specifically by the CFTC. And so it could be the case that we don’t have a circuit split, to be totally honest, because it could be the case that the Fourth, the Ninth, the Sixth also come out in favor of the prediction markets. The only decision so far has been in favor of exclusive jurisdiction. So maybe it gets more quickly resolved in that way, but I have no doubt that folks will appeal as well.
DL: Now let’s turn to my speed round. These are four standard questions, and they’re the same for all my guests.
My first question is, what do you like the least about the law? And this can either be the practice of law or law as an abstract system.
MA: EDGAR is just such an arcane system, but I have a different one: PACER. It makes me crazy that given the open nature of our court system, and the fact that we almost never have closed proceedings, you still need this fancy login that changes from one jurisdiction to the next, and you pay 10 cents per page to download something. If I were ever to do a startup of my own, and maybe it would just be a nonprofit, I would open-source all court pleadings and decisions and make it more easily accessible. Maybe LLMs will be our answer. But it makes me absolutely crazy how difficult and inaccessible tools like PACER are.
DL: I totally agree. And there are definitely organizations out there like Fix the Court, which are quite focused on this issue, so maybe we’ll see some progress.
My second question is, what would you be if you were not a lawyer?
MA: So I’m not going to say engineer here; I’m actually going to say doctor. I also took all of the classes to be able to go to medical school because I just like hard, intense things. I don’t know—maybe I’ll be a doctor in my 50s.
DL: That’s funny. My husband Zach had a law school classmate in his 50s who was a former doctor, so you could go the other way.
My third question is, how much sleep do you get each night?
MA: Six and a half hours exactly, and without fail.
DL: Wow. Do you have a fixed bedtime and wake-up time?
MA: I do. I wake up every day at 4:38, and I’ve figured this out quite exactly, David—it’s been the unlock of productivity for me—which is that 22 minutes is how much time I need to get up, get dressed, brush my teeth, read the news, and get ready for a 5:00 a.m. workout. I have found that if I can start my day that way, having cleared the decks and then exercised, it makes me a much more pleasant parent and manager.
DL: Well, I’m going to have to talk to you offline about tips on that. My last question is, any final words of wisdom, such as career advice or life advice, for my listeners?
MA: Yes. Make yourself dispensable. I think that too often people view their roles at companies, at law firms, you name it, as, “This place needs to fall apart without me, or I won’t be valued, or I won’t have career security.” And the thing that I have really about 10 years ago taken the point of view on is if I can make myself dispensable because I’ve scaled myself so well, I’ve trained people around me to be able to take tasks, I’ve given people visibility, it actually has been the reason that I’ve been able to take on more at every turn. So I would say, make yourself dispensable.
DL: Well, that is definitely a new and unusual perspective—but as to this conversation, you were indispensable. Molly, thank you so much for joining me.
MA: It was a pleasure. Thank you so much, David.
DL: Thanks so much to Molly for joining me, and congratulations to her on becoming the GC of Coinbase.
Thanks again to NexFirm for sponsoring the Original Jurisdiction podcast. NexFirm helps boutique law firms offer Biglaw-caliber benefits at small-firm prices. To learn how NexFirm can help your firm attract and retain exceptional talent, call 212-292-1002 or email betterbenefits@nexfirm.com.
Thanks to Tommy Harron, my sound engineer here at Original Jurisdiction, and thanks to you, my listeners and readers. To connect with me, please email me at davidlat@substack.com, or find me on Twitter, Facebook, and LinkedIn, at davidlat, and on Instagram and Threads at davidbenjaminlat.
If you enjoyed today’s episode, please rate, review, and subscribe. Please subscribe to the Original Jurisdiction newsletter if you don’t already, over at davidlat.substack.com. This podcast is free, but it’s made possible by paid subscriptions to the newsletter.
The next episode should appear on or about Wednesday, September 2. Until then, may your thinking be original and your jurisdiction free of defects.
[UPDATE (8/29/2026, 11:12 p.m.): For more about Molly Abraham, see Brian Baxter’s profile of her for Bloomberg Law, which covers a number of the topics we discussed in our conversation.]
Thanks for reading Original Jurisdiction, and thanks to my paid subscribers for making this publication possible. Subscribers get (1) access to Judicial Notice, my time-saving weekly roundup of the most notable news in the legal world; (2) additional stories reserved for paid subscribers; and (3) the ability to comment on posts. You can email me at davidlat@substack.com with questions or comments, and you can share this post or subscribe using the buttons below.


